Drafted 10/01/2026
Published 10/02/2026
DOWNLOAD THE PDF VERSION OF THIS REPORT HERE
OVERVIEW
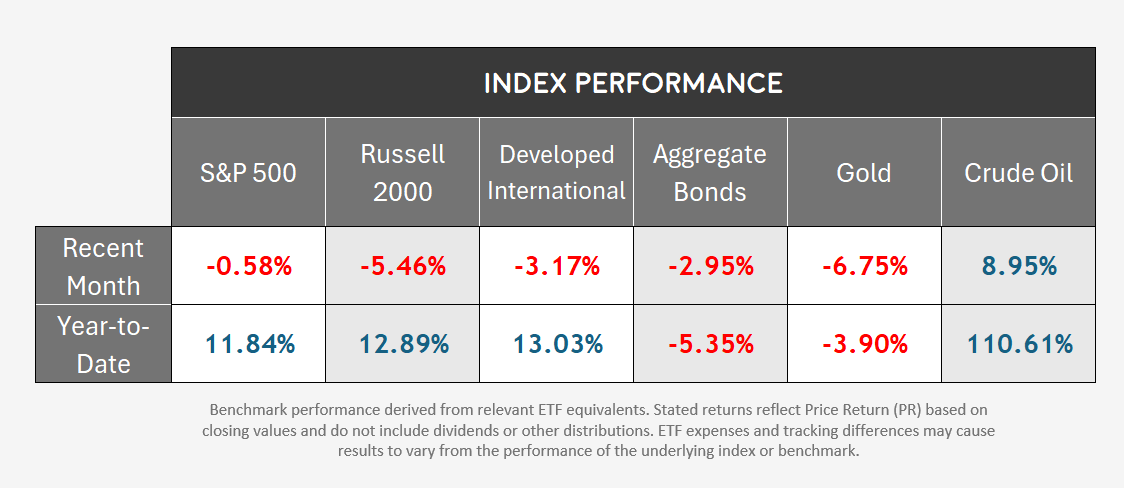
Markets were generally down in September, with equity selling particularly seen in small-cap and international stocks (both prone to weakness during a rising rate environment). While the S&P 500 declined only 0.58% for the month, this masks underlying weakness in the index. By month end, only 22% of stocks were above their 20-day moving average.
Oil and bonds climbed in unison during the month, with rising yields causing bond fund values to fall sharply. Gold also sold off and is now negative for the year.
With stock values declining but profits climbing, on a forward-earnings basis equities are at their cheapest valuation since March. As we move into the next stock “earnings season” in October, we anticipate stocks to reprice in the face of positive news, though this may not happen immediately if bond yields remain elevated.
LIFETIME MOMENTUM & VOLATILITY INDEX (LMVI)
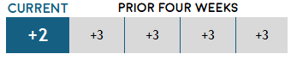
We maintain an index designed to measure short-term stock market momentum and volatility. The Lifetime Momentum & Volatility Index (LMVI) provides guidance on when to adopt a more conservative or aggressive posture within portfolios. The idea is not to “time the market”, but to identify periods of elevated risk or improving conditions.
The LMVI turned negative (risk-off) in February. However, since April 3rd it has returned a consistently positive value. The current reading of +2 (on a scale of -4 to +4) reflects that volatility has declined, though market momentum has been a struggle recently. The positive score encourages a fuller expression of risk within portfolios.
Download the most recent LMVI Report HERE
LIFETIME EARLY WARNING SYSTEM (LEWS)
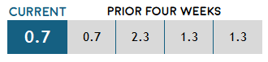
Lifetime Retirement Partners maintains an index which measures economic fragility. The Early Warning System is not intended to be a recession predictor, per se, but is calibrated to score eight market and economic indicators which tend to be leading indicators of structural weakness.
While the score ticked up slightly at the onset of the Iran conflict (and subsequent market sell-off), the current score of 0.7 is the lowest score in the last year. This indicates very little fragility in the economy. This isn’t predictive that investments will appreciate, but it does indicate a clear economic runway with a lack of fundamental stress.
Download the most recent LEWS Report HERE
MACROECONOMIC INDICATORS
Our proprietary economic database evaluates Macroeconomic Indicators across two separate categories: Real Consumer Demand and Economic Growth and Activity. The score remains positive, where it has resided for over a year, reflecting a stable economic backdrop.
REAL CONSUMER DEMAND: Inflation remains a key pressure point for both the economy and the consumer. The latest Personal Consumption Expenditures (PCE) inflation reading is higher than a year ago and pricing pressures have reasserted themselves.
ECONOMIC GROWTH & ACTIVITY: The economy continues to grow, with real GDP (above inflation) of 2.2% last quarter. Broader measures such as Gross Output, continued expansion across services and manufacturing sectors, and additional production indicators (including truck tonnage shipped) reinforce the view of continued expansion.
View our most recent Macroeconomic slide deck HERE
MONETARY INDICATORS
Our proprietary economic database evaluates Monetary Indicators across two separate categories: Federal Policy & Lending & Liquidity. The score reduced from +2 to +1 in July and has remained at this level. The score decline represented the diminished prospect of rate cuts (and, in fact, we’ve moved into rate hikes), along with an increase in dollars in circulation (M2). Private liquidity remains excellent.
FEDERAL POLICY: With inflation reasserting, the Fed opted to hike rates in September, bringing a prior cutting cycle to an end. We are concerned that Money Supply (M2), now growing at a year-over-year rate of 5.3%, will make inflation hard to contain.
LENDING & LIQUIDITY: Bank lending has steadily increased over the past year, supporting economic activity. Business loan delinquencies have declined fractionally over the last year. There seems to be little underlying stress in the financial sector.
View our most recent Monetary slide deck HERE
CONSUMER STRENGTH INDICATORS
Our proprietary economic database evaluates consumer strength across two primary areas: Employment and Consumer Health. The current overall score is +2 (positive), reflecting a stabilization from earlier weakness (the score was negative to start the year).
EMPLOYMENT: Where we previously characterized the labor market as a “low hire, low fire” environment, improvements over the year indicate not just a stable labor environment but a strengthening one. Initial jobless claims remain low, unemployment has declined year-over-year, and the number of available jobs has increased during 2026.
CONSUMER HEALTH: While concerns around a stretched consumer persist, the data remains more balanced than media narratives suggest. Household debt has increased year-over-year but at a moderate historical pace. Consumer delinquency rates have not climbed over the last year. While wages climbed slower than rebounding inflation last quarter, they had climbed faster than inflation for the twelve prior quarters.
View our most recent Consumer slide deck HERE
MARKET FUNDAMENTALS
While our framework does not assign a formal score to stock market fundamentals, the current assessment remains positive, reflecting a broadly supportive backdrop for equities.
Stocks in the S&P 500 delivered extremely strong second-quarter earnings. With 99% of businesses reporting, 87% of companies exceeded earnings estimates. Even after excluding large investment gains reported by Amazon and Alphabet, the aggregate earnings surprise was 10.8%, well above historical averages.
On a forward price-to-earnings basis, the S&P 500 (currently 19.17) is the cheapest it has been since March; the point at which the market started a significant rebound. While the S&P 500 is up for the year, on both a “current” and “forward” basis stocks are cheaper than they were at the beginning of 2026. The market has remained restrained. Not only has there been no “multiple expansion,” but we have witnessed modest multiple contraction.
We continue to score the stock market with a positive lean, though there are concerns. Market breadth deteriorated over September as bond yields surged and oil spiked. Rising rates put pressure on stocks, just as they do on existing bonds. However, the predominant environment is one in which individual corporations have continued to overperform expectations. We expect that stocks will eventually re-anchor to this fact.
View our most recent Market Fundamentals slide deck HERE
CONCLUSION
The overall condition remains positive for the stock market and economy, though inflationary headwinds persist. Many stocks have been attractively repriced.
The rate hike cycle which we seem to be entering, along with the upcoming mid-term election, gives us pause in predicting a near-term rally. We remain expectant that stocks will climb to correlate with continued strength in corporate earnings over the next six-to-twelve months, but that does not mean that it will happen immediately or that it will be a smooth ride.